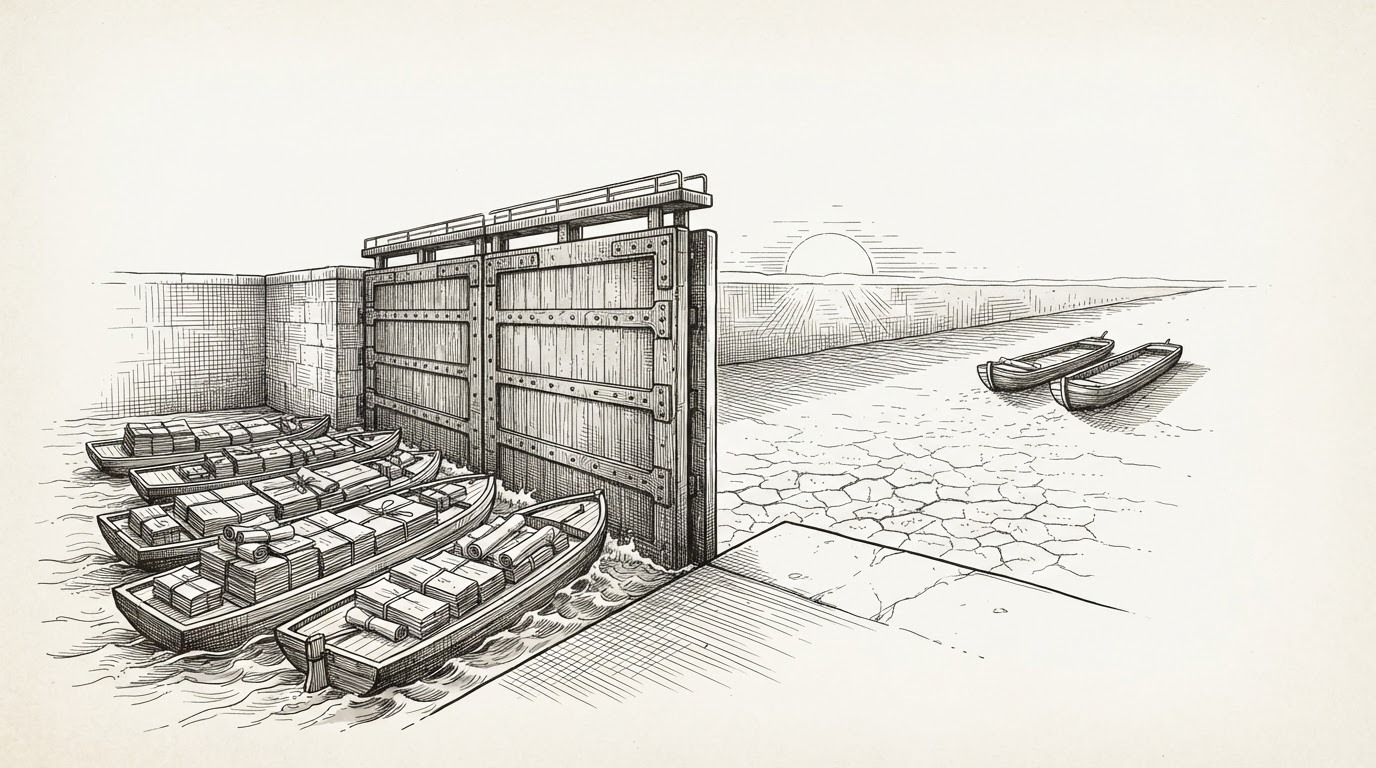
The arithmetic is the story: 87 days separate the October 23, 2026, delivery of the GENIUS Act’s stablecoin application forms to the Office of Management and Budget from the January 18, 2027, compliance date fixed by the GENIUS Act final rule. That gap is the entire runway between a rule that is final and a filing door that remains bolted shut. What fills it is not market speed, but the deliberate sequence of federal review.
The stakes are not abstract. Under the OCC’s waiver guidance, issuing a payment stablecoin in the United States without prior approval after January 18, 2027, carries criminal penalties – and the statute offers no compliance implementation process for the issuers already operating here. Yet as of October 28, 2026, the channel is closed by design: the OCC cannot accept applications until OMB gives final approval of the information collection, and even then the agency must issue a separate press release to open the window. As the rulebook coverage noted, the chassis is finished; the front door is not.
That collection, information collection 1557-NEW, entered OMB’s 30-day review on October 23, with comments due November 23. It has not been approved, no application form has been released, and no window-opening press release exists. Every day of the wait consumes the runway issuers will need – the same dateless window tax already mapped against new entrants, now with a clock on it courtesy of the OMB submission itself.
The exit is the waiver pathway of Section 5(f), carried into the final rule at section 15.30(g). Any issuer with a substantially complete application pending at the OCC on or before January 18 may ask to waive requirements it cannot meet by the deadline, for up to 12 months. The OCC’s posture is unusually direct: it generally expects to grant those waivers to existing US issuers. The bulletin’s own logic is blunter still: without a waiver, an incumbent that files a substantially complete application on time could nonetheless be violating the law on January 18 if it keeps issuing – and avoiding that disruption, along with what it calls potential inequity to existing issuers, is named as a compelling reason to grant relief.
The review clocks then stack against a deadline that will not move. The OCC has 30 days to determine whether an application is substantially complete; a deficiency notice buys the applicant another 30-day exchange; an application still incomplete is returned no later than 60 days after the initial notice; and a decision comes no later than 120 days after a substantially complete finding. The agency says it will act on waiver requests in a timely manner and generally by January 18, 2027, and its instruction to covered applicants is to file as soon as practicable after the window opens. If OMB approval lands in late December, the window between the press release and the compliance date may measure in days, not weeks.
Outside the door, prospective issuers get none of this. The OCC has identified no generally applicable reasons to waive section 5(f) for players not currently operating in the United States – consistent with charter practice, they begin operations only after approval. Nor has it found compelling reasons to waive anything beyond the Prior Approval Requirement itself: incumbents, the bulletin notes, have had 18 months since the act’s passage to prepare. Secondary-sourced forecasts of the OCC’s economic analysis suggest roughly 22 issuers may seek approval, with issuance reaching about $378.8 billion in 2027 and $765 billion in 2028 – estimates drawn from coverage of the rule’s economic modeling, not commitments by anyone.
The softened moat logic from the yield fight applies here too: the waiver bridge exists only for whoever is standing on the incumbent side of it when the press release lands. The next gate is November 23’s comment close, then OMB approval, then the OCC’s announcement. The 87-day countdown runs through all three, indifferent to who has finished preparing.